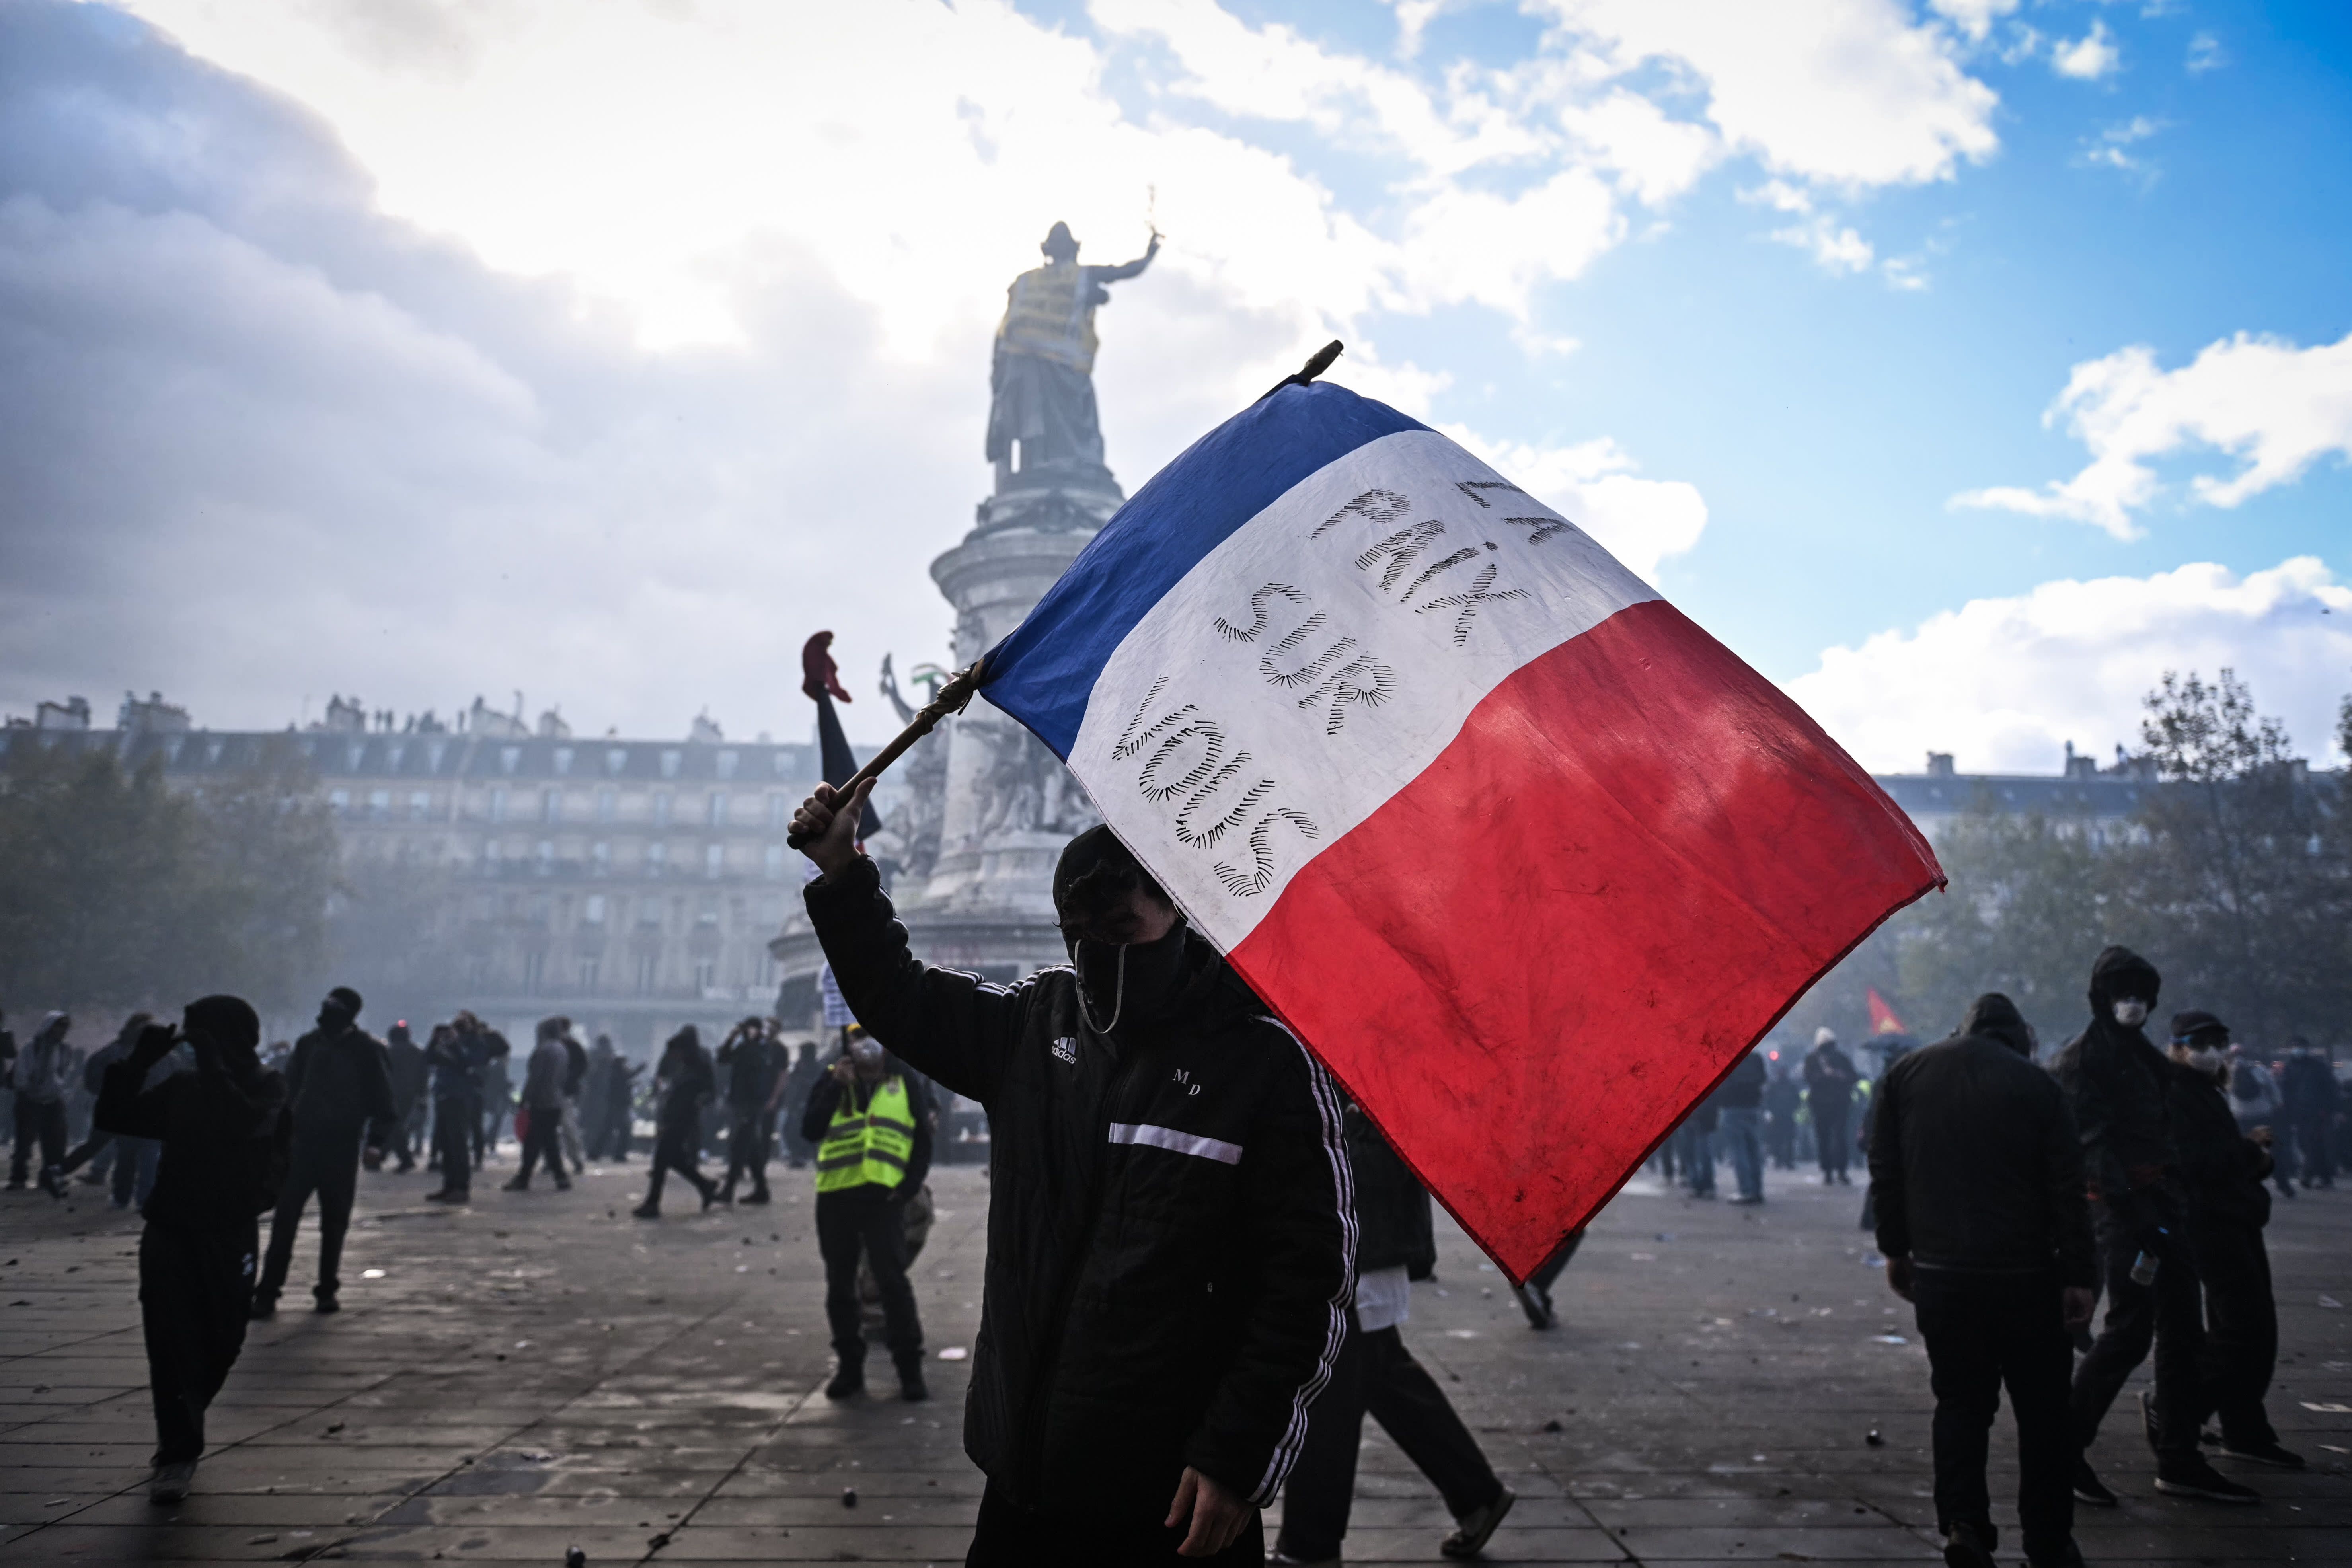
Unrest in France is deepening investor concerns about the country's fiscal outlook, after benchmark borrowing costs climbed to their highest level since 2002 this week, with further demonstrations planned.
The yield on benchmark 10-year French government bonds, known as OATs, rose 11 basis points on Thursday, pushing the spread over 10-year German Bunds — the euro zone debt benchmark — to its widest since November 2011. Fund managers are assessing whether prolonged disruption could weaken growth, undermine confidence and complicate the government's planned budget savings.
Rating agency Moody's on Friday kept its Aa3 credit rating on France, which it still deems "high grade," but maintained a negative outlook. Moody's said the outlook "reflects the increased risk that the fragmentation of France's political landscape will continue to impair the functioning of the country's legislative institutions," adding it could return to a stable outlook if institutions narrow the budget deficit.
France's government aims to cut the budget deficit to 5% of GDP in 2027, down from a projected 5.4% in 2026. The National Assembly is due to resume debate on the budget's tax measures on Oct. 27, though opposition lawmakers are resisting the plans.
Alain Durré, head of EMEA economic research at Natixis CIB, said the government could try to stick to its fiscal targets by invoking Article 49.3 — which allows it to push a bill through the assembly without a final vote unless lawmakers pass a no-confidence motion — or by using executive ordinances. He noted recent pressure on French debt has been driven mainly by tactical portfolio reallocations, with traditional buy-and-hold investors "still sitting on the sidelines."